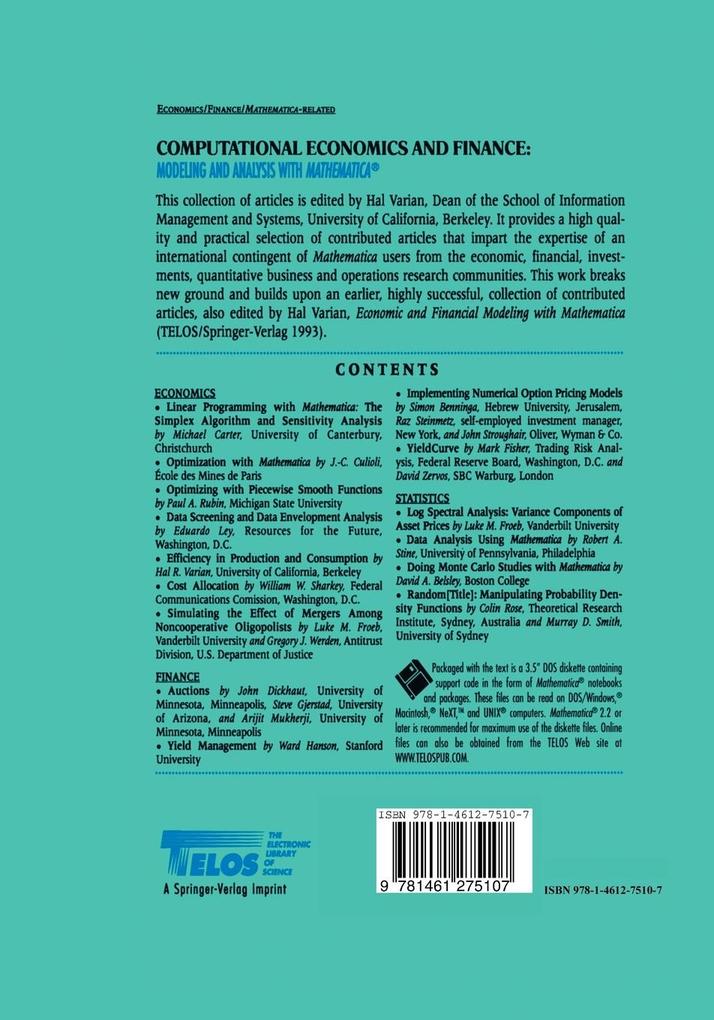
As with the first volume, Volume Two of Economic and Financial Modeling with Mathematica is edited by Hal Varian, and its contributors are carefully selected by him to assure a high quality, practical work reflecting the efforts and expertise of an international cadre of Mathematica users from the economic, financial, investments, quantitative business and operations research communities.
Inhaltsverzeichnis
Economics. - 1 Linear Programming with Mathematica: The Simplex Algorithm. - 2 Linear Programming with Mathematica: Sensitivity Analysis. - 3 Optimization with Mathematica. - 4 Optimizing with Piecewise Smooth Functions. - 5 Data Screening and Data Envelopment Analysis. - 6 Efficiency in Production and Consumption. - 7 Cost Allocation. - 8 Simulating the Effects of Mergers Among Noncooperative Oligopolists. - Finance. - 9 Auctions. - 10 Yield Management. - 11 Implementing Numerical Option Pricing Models. - 12 YieldCurve. - Statistics. - 13 Log Spectral Analysis: Variance Components of Asset Prices. - 14 Data Analysis Using Mathematica. - 15 Doing Monte Carlo Studies with Mathematica. - 16 Random[Title]: Manipulating Probability Density Functions.